
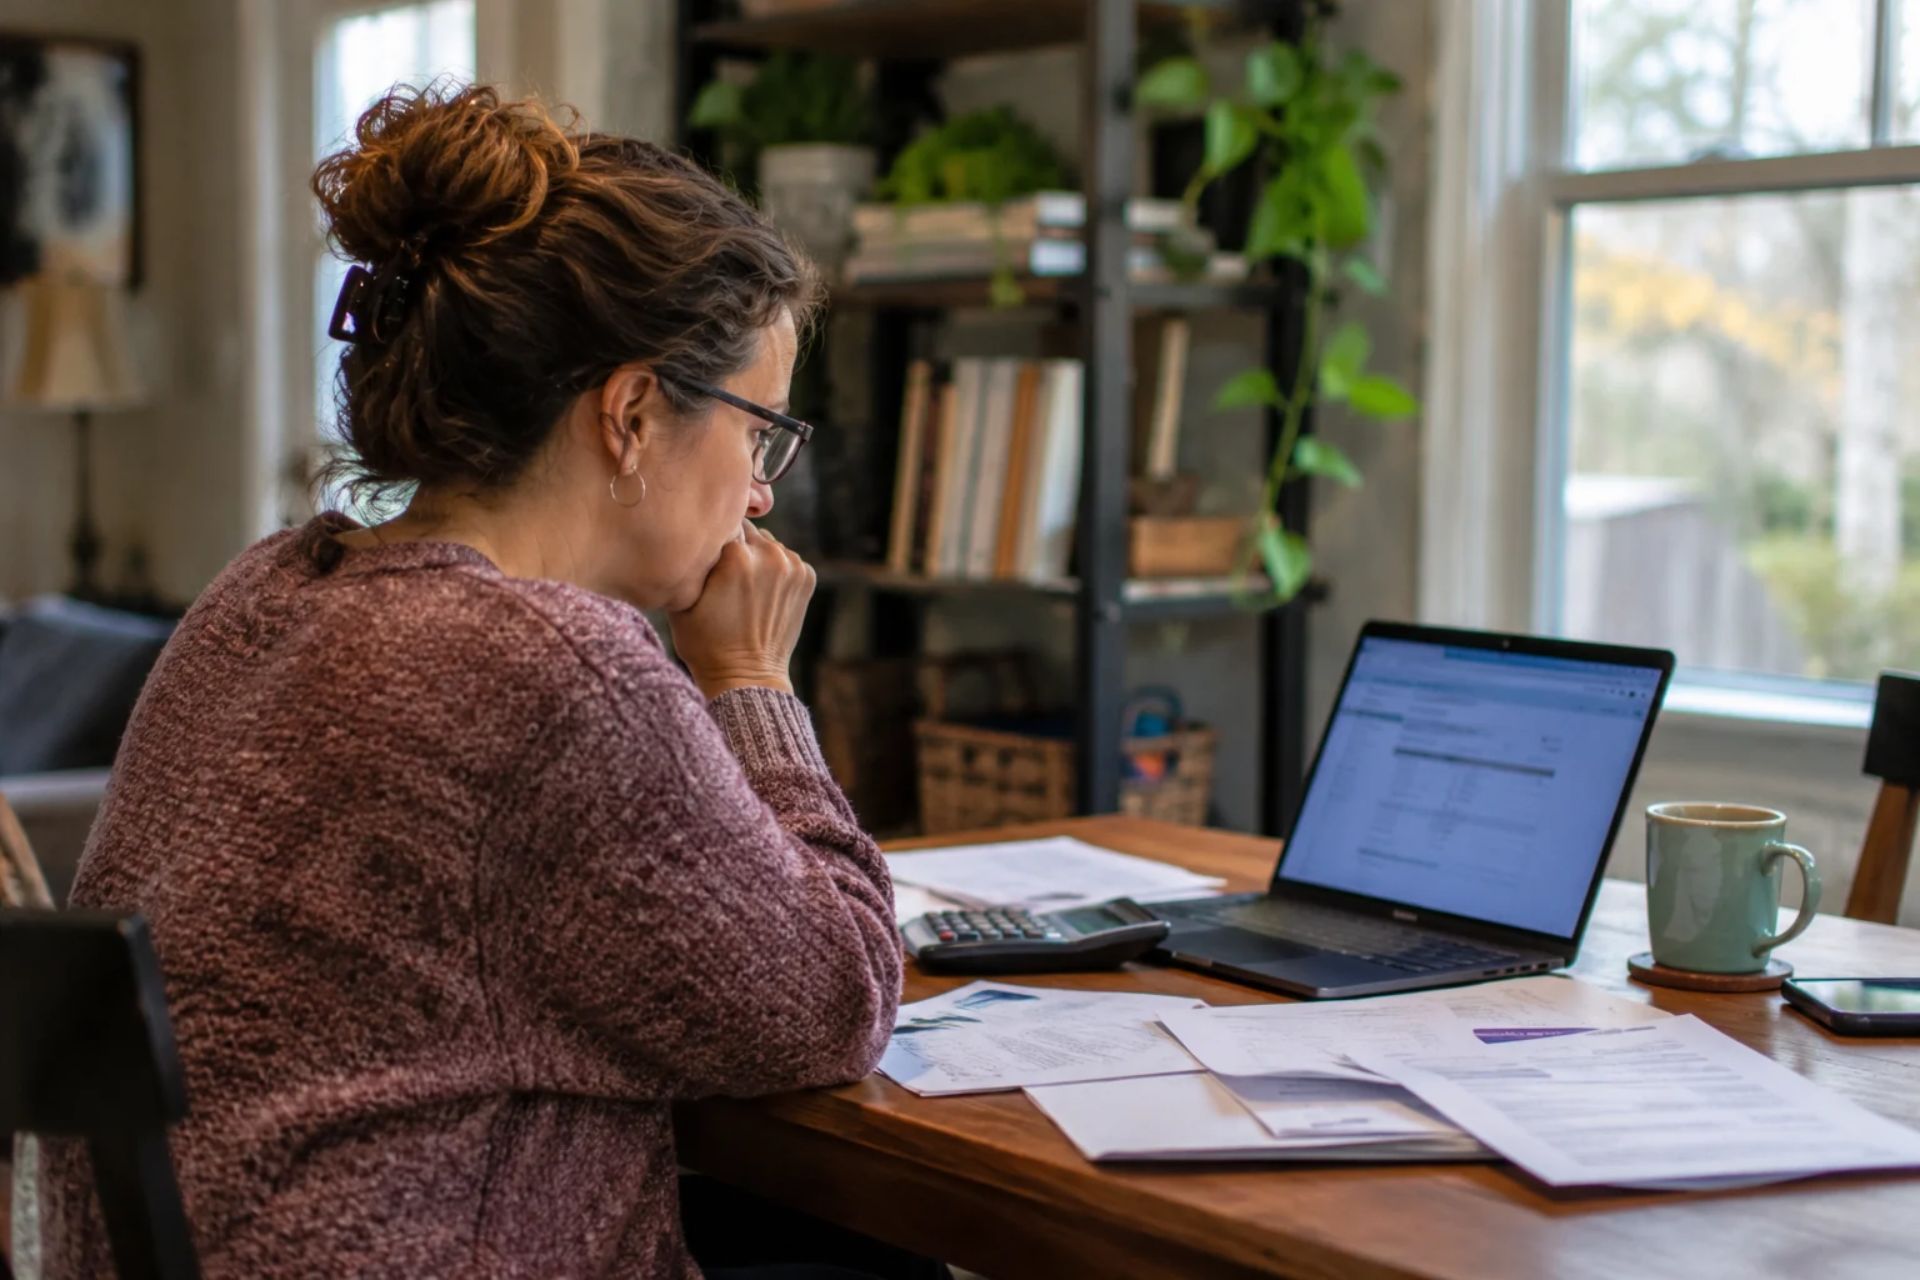
A phishing text that looks like it came from your bank. A ransomware pop-up on the family laptop holding ten years of photos. A group chat that turns cruel toward your teenager. These things happen in ordinary Colorado households every week, and most homeowners policies were never built to handle them. Personal cyber insurance fills that gap with money for online fraud and ransomware losses, help with cyberbullying, data recovery, and expert support when something goes wrong. Coverage is often inexpensive, but the details vary a lot between carriers. Here's how this coverage works and what it actually pays for.
Why Your Home Network Needs Professional Protection
The numbers are hard to ignore. Americans lost an estimated $21 billion to online fraud in 2025, across more than 1 million reported incidents. Imposter scams alone accounted for $3.5 billion, and one in three fraud reports involved someone pretending to be a bank, a government agency, or a family member.
Older adults carry a heavy share of that loss. People over 60 lost nearly $5 billion to cyber fraud in 2024. If you help aging parents manage their accounts, their risk is part of your household's risk.
Confidence is falling too. Only
32% of Americans feel confident their sensitive data stays private in 2026, down from 48% a year earlier. Antivirus software and strong passwords lower your odds. They won't refund a wire transfer or pay a data recovery specialist.
By: Brian J. Cook
Founder & Managing Partner of The Insurance Loft
Core Coverages: From Financial Fraud to Data Recovery
Most personal cyber policies combine reimbursement for money you lose with paid services that help you recover. Typical coverage parts include:
- Online fraud: Money lost to phishing, fake invoices, or unauthorized transfers
- Data recovery: Costs to restore files, photos, and software after an attack
- System restoration: Repairing or reinstalling compromised devices
- Cyber extortion: Ransom response and negotiation
- Identity restoration: Case managers who handle credit bureaus and creditors
Combating Ransomware and Identity Theft
Ransomware no longer targets only businesses. A home office laptop or a smart home hub can get locked just as easily. Better policies now follow an "active" model, with 24/7 incident response, forensic support, and professional ransomware negotiators. That help matters more than the payout, because paying a ransom without guidance can make things worse.
Identity theft claims usually cover legal fees, lost wages for time spent fixing the damage, and notarization and mailing costs.
Support for Cyberbullying and Reputation Management
This is the coverage parents ask about most. Depending on the policy, it can pay for counseling, temporary relocation or tutoring if a child has to change schools, legal costs, and removal of harmful content. Read the definitions closely. Some policies require a documented, ongoing pattern of harassment, so a single incident may not qualify.
Comparing Standard Homeowners Policies vs. Personal Cyber Insurance
A common client mistake is assuming homeowners coverage already includes this. It usually doesn't, or it caps identity theft help at a token amount.
| Risk | Standard Homeowners | Personal Cyber Coverage |
|---|---|---|
| Phishing/wire fraud | Rarely covered | Covered |
| Ransomware response | Not covered | Covered, with negotiators |
| Data recovery | Not covered | Covered |
| Cyberbullying costs | Not covered | Often covered |
| Identity theft | Limited, if any | Expanded with case managers |
| Typical cost | Base premium | About $25-$75/year as endorsement |
Added as an endorsement to a homeowners or renters policy, cyber coverage typically costs $25 to $75 per year. That's less than most streaming bundles.
Common Questions About Personal Cyber Coverage
Is personal cyber insurance worth it if I'm careful online? Usually, yes. Imposter scams fool cautious people too, and coverage also protects family members who may be less careful.
Can I buy it without a homeowners policy? Some carriers sell it as a standalone policy. Most people add it to a homeowners or renters policy because that's cheaper.
Does it cover cryptocurrency losses? Often not, or only with tight limits. Investment fraud led reported losses at $8.65 billion of the $20.88 billion total in 2025, so check this exclusion if you hold digital assets.
Are my kids covered? Most policies cover household members, including children living at home and students away at college.
What should I do first after an attack? Call your carrier's incident hotline before paying anyone or wiping devices. Responders need the evidence.
Making the Right Choice for Your Digital Security
Not every endorsement is equal. Some carriers cap fraud reimbursement at $10,000. Others offer $50,000 or more with full ransomware response. Compare policies with matching limits and deductibles so you're comparing like with like, and review your coverage every year as your household adds devices, teens get phones, or parents need help managing money.
Claims are getting more complex. Even as AI detection has steadied how often claims happen, the average severity of large incidents has doubled to $4.4 million in commercial cyber. That pressure shapes how carriers write personal policies too.
The best coverage for online fraud, ransomware, and cyberbullying is the policy that matches how your family actually lives online. The Insurance Loft is an independent agency, so a licensed advisor can compare cyber endorsements from carriers like Chubb, Travelers, Safeco, and Nationwide side by side. Reach out for a review of your current policy and find out what you're missing before a scammer does.
COVERAGE FOR YOUR LIFE
Personal Insurance Plans That Protect What Matters Most
From your home and car to your family and pets — we cover it all.
GET THE ANSWERS YOU NEED
Common Questions About The Insurance Loft
We believe informed clients make better coverage decisions. Here are the questions we hear most often.
What does it mean to be an independent insurance agency?
An independent insurance agency like The Insurance Loft is not tied to a single insurance company. We are licensed to work with multiple carriers — including Nationwide, Travelers, Progressive, Safeco, Chubb, and others — so we can compare options and find the best policy for your needs. When you work with a captive agent, you only see what that one company offers. When you work with us, you see the full market.
This independence also means we represent you, not the carrier. When a claim arises or your coverage needs to change, your advisor advocates for your interests — not the insurance company's bottom line. That is the core of what makes The Insurance Loft different.
Where is The Insurance Loft located and who do you serve?
The Insurance Loft is headquartered in Greenwood Village, Colorado, in the Denver Tech Center area. We serve individuals and families throughout Colorado — from the Denver Metro and Front Range to Colorado Springs, Boulder, Fort Collins, mountain communities, and beyond. Our office is conveniently located at 5990 Greenwood Plaza Blvd, Ste 270, Greenwood Village, CO 80111.
Whether you are a longtime Colorado resident or just moved to the state, The Insurance Loft can help you find the right personal insurance coverage. Our advisors understand Colorado's specific risks and regulations, and they know which carriers offer the best coverage options for your area. Call us at 800-409-9790 or schedule a call online to get started.
What types of insurance does The Insurance Loft offer?
We offer a full range of personal and commercial insurance products. On the personal side, we cover home, auto, renters, life, motorcycle, umbrella, and pet insurance. For businesses, we provide general liability, commercial property, workers compensation, professional liability, business auto, and specialty coverage for industries like construction, food and beverage, brewery, and cannabis operations.
We also offer surety bonds for businesses that require them. Our goal is to be your single resource for every insurance need — personal or commercial — throughout your life and the life of your business. If you are unsure what coverage you need, schedule a call and an advisor will walk you through your options at no cost.
What carriers does The Insurance Loft work with?
The Insurance Loft partners with more than 19 trusted insurance carriers to give clients access to a wide range of options. Our featured carrier partners include Nationwide, Travelers, Progressive, Safeco Insurance, Chubb, and Hagerty Insurance for collector vehicles. Each carrier brings different strengths, pricing structures, and coverage specialties, which is why having access to multiple companies matters.
Because we work with a diverse group of carriers, we are not pressured to place policies with any single company. Your advisor reviews your situation, identifies which carriers best match your needs, and presents your options clearly. This process consistently delivers better coverage at competitive prices compared to going directly to a single insurance company.
How does The Insurance Loft handle the claims process ?
When you need to file a claim, your dedicated Insurance Loft advisor is your first call. We provide claims support through our Member Services team and guide you through the process with your carrier. You will not be left to figure it out alone. Our advisors help you understand what your policy covers, what documentation is needed, and what to expect from the timeline.
You can also access claims support directly through our Member Services portal at theinsuranceloft.com. Our goal is to make the claims process as clear and stress-free as possible so you can focus on recovery. For urgent claims assistance, contact our Customer Care team at 800-409-9790 during business hours, Monday through Friday, 9 AM to 6 PM.
Why should I review my insurance coverage every year?
Your life changes constantly — and your insurance should change with it. A new home, a new vehicle, a renovation, a new employee, a business expansion, or a change in your income can all affect how much coverage you need. Reviewing your policy annually helps make sure you are not paying for coverage you no longer need, and that you are not underinsured in areas where your exposure has grown.
The Insurance Loft advisors proactively reach out at renewal time to review your current policies and flag anything that needs attention. Major life events like buying a home, starting a business, getting married, or having children are all good reasons to schedule an earlier review. Contact your advisor or call 800-409-9790 to set up a coverage review at any time.
INSURANCE KNOWLEDGE, MADE SIMPLE
Learn From Our Resource Center
Practical answers to real insurance questions — written by the advisors who help clients every day.
CONTACT US
Phone Number: 1-800-409-9790