See How We're Different
Call Us: 1-800-409-9790
Buying a car in Colorado right now means confronting some uncomfortable math. New vehicle transaction prices have climbed to roughly $50,089 as of mid-2026, and even used cars are sitting about 20% above pre-pandemic levels. That means more drivers are financing larger amounts, stretching loan terms longer, and putting less money down just to keep monthly payments manageable. The result? A growing number of Colorado drivers owe more on their car than it's actually worth, sometimes for years after they drive off the lot.
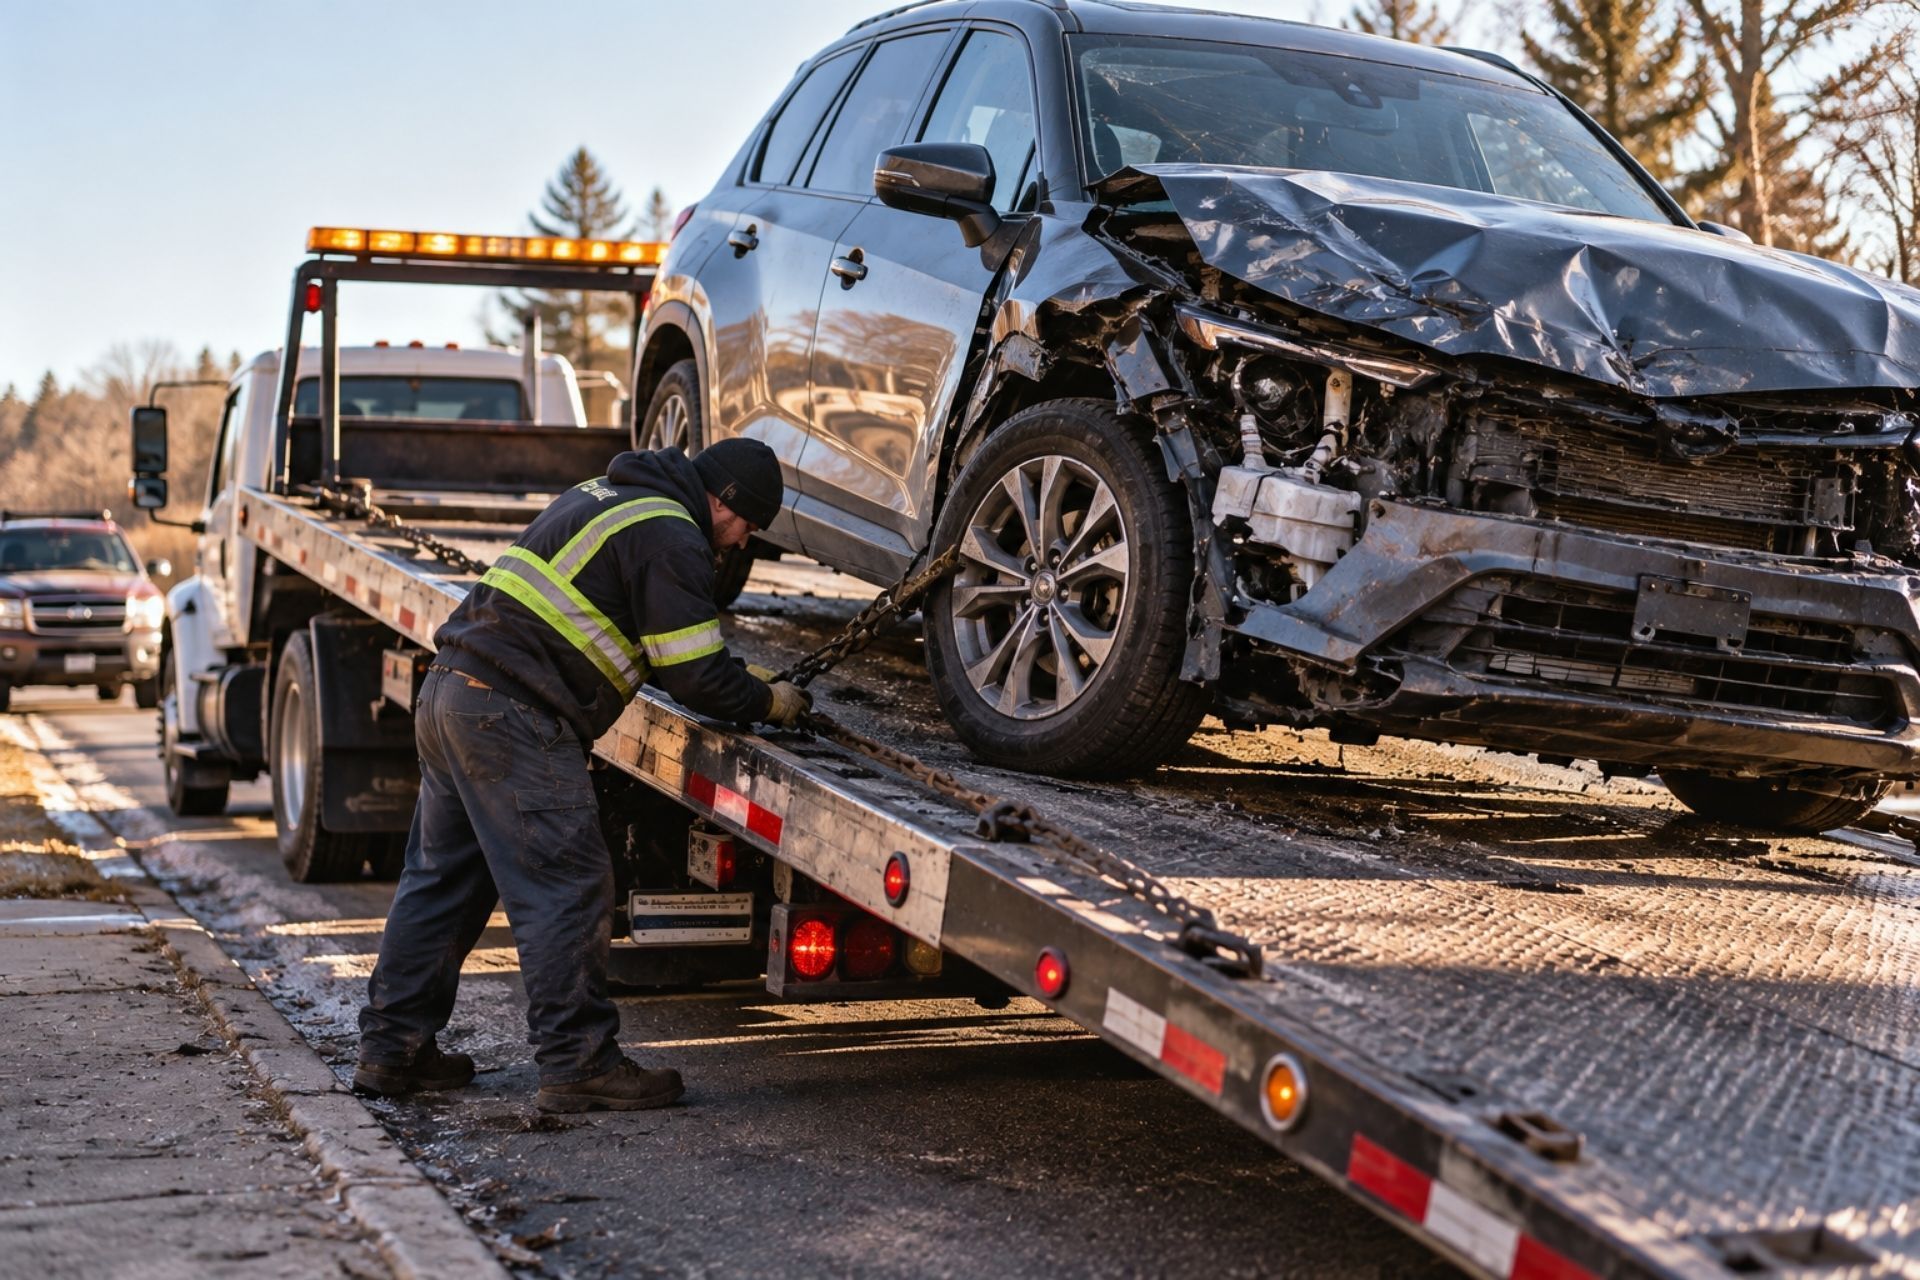
This is exactly the scenario gap insurance was designed for. If your car gets totaled or stolen, your standard auto policy pays out the vehicle's current market value, not what you still owe the bank. That difference, the "gap," can easily run $5,000 to $10,000 or more on a newer vehicle. For drivers with leased or financed cars in Colorado, understanding whether gap coverage makes sense is less about checking a box and more about protecting yourself from a financial hit you didn't see coming.
Here's what you need to know about how it works, what it costs, and whether it's worth your money.
Understanding Gap Insurance in the Colorado Market
Gap insurance exists for one reason: cars lose value faster than most people pay them off. If you finance $45,000 on a new SUV and it's worth $32,000 eighteen months later, you've got a $13,000 problem if it gets totaled. Your collision or comprehensive coverage pays the $32,000 market value. You still owe the lender the remaining balance. Gap coverage picks up that difference so you're not writing a check for a car you can no longer drive.
Colorado's Front Range hail season makes this especially relevant. A single spring storm can total hundreds of vehicles in a matter of minutes, and if your car is one of them, you want to know the math works in your favor.
How Gap Coverage Works with Standard Policies
Your standard auto insurance policy, whether it's collision or comprehensive, pays based on actual cash value (ACV) at the time of a loss. ACV factors in depreciation, mileage, condition, and local market prices. It does not factor in what you owe your lender.
Gap insurance activates only after your primary insurer has paid out. It covers the remaining loan or lease balance minus your ACV payout. Think of it as a bridge between two numbers that should be the same but almost never are in the early years of a loan.
One thing to keep in mind: gap coverage only applies to total loss or theft situations. It won't help with fender benders, partial damage, or mechanical breakdowns.
The Impact of High Depreciation Rates
New cars typically lose 20% to 30% of their value in the first year alone. Some models depreciate even faster, especially if a manufacturer releases a redesign or demand shifts toward EVs. In Colorado, where many drivers favor trucks and SUVs with higher sticker prices, the dollar amount of that depreciation can be staggering.
A $55,000 truck that loses 25% in year one is now worth around $41,000. If you financed the full amount over 72 months with a modest down payment, you could easily owe $48,000 or more at the 12-month mark. That's a $7,000 gap, and it only gets worse with longer loan terms or higher interest rates.
When Colorado Drivers Benefit Most from Coverage
Not every driver needs gap insurance. If you paid cash for your car or put 40% down, you're probably fine. But certain financial situations make gap coverage a smart move, and they're more common than people realize.
Low Down Payments and Long-Term Loans
The drivers who benefit most from gap coverage are those who put little or nothing down and stretch their loans to 72 or 84 months. This combination almost guarantees you'll be "upside down" on the loan for the first several years.
Here's a quick way to think about it:
- Down payment under 20%? You're likely underwater from day one.
- Loan term of 60 months or longer? You'll stay underwater longer.
- Interest rate above 6%? More of your early payments go to interest, not principal.
- Rolling negative equity from a trade-in? You're starting even deeper in the hole.
If two or more of those apply to you, gap insurance deserves serious consideration.
Leasing a Vehicle in Colorado
Leased vehicles are a natural fit for gap coverage because you never build equity in the car. You're essentially paying for depreciation, and if the car is totaled, you're on the hook for the remaining lease payments minus the vehicle's market value.
Many lease agreements in Colorado actually include gap protection built into the contract, but not all do. Read the fine print. If your lease doesn't include it, adding gap coverage through your auto insurer is usually inexpensive and well worth the protection. An independent brokerage like The Insurance Loft can help you check your lease terms and figure out whether you need a separate policy.
Comparing Coverage: Comprehensive vs. Gap Insurance
People sometimes confuse comprehensive coverage with gap insurance, assuming one does the job of the other. They serve completely different purposes.
Comprehensive covers damage from events outside your control: hail, theft, flooding, vandalism, animal strikes. Collision covers damage from accidents. Both pay out based on your car's actual cash value. Neither one cares what you owe the bank.
Gap insurance only kicks in after one of those policies has already paid. It covers the financial shortfall between the insurance payout and your remaining loan or lease balance.
Comparison Table: What Each Policy Pays For
Comparison of Coverage Limits and Deductibles
| Scenario | Comprehensive/Collision | Gap Insurance |
|---|---|---|
| Hail totals your car | Pays actual cash value minus deductible | Pays remaining loan balance minus ACV payout |
| Car is stolen and not recovered | Pays actual cash value minus deductible | Pays remaining loan balance minus ACV payout |
| Fender bender | Pays repair costs minus deductible | Does not apply |
| You owe less than the car is worth | Pays actual cash value minus deductible | Nothing to pay: no gap exists |
| Mechanical breakdown | Does not apply | Does not apply |
The key takeaway from this table: gap insurance is only useful when you owe more than your car's market value and a total loss occurs. It's a targeted protection, not a catch-all.
Colorado Legal and Financial Considerations
Colorado has specific rules around gap insurance that work in the consumer's favor, and they're worth knowing before you sign anything at a dealership.
State Requirements and Lender Mandates
Colorado passed HB23-1181, which places specific requirements and fee caps on gap waiver agreements sold through dealerships. Under this law, creditors cannot charge a gap fee that exceeds 4% of the total amount financed or $600, whichever is greater. This protects buyers from inflated gap fees that some dealerships used to tack on without much explanation.
No Colorado law requires you to carry gap insurance. Some lenders may require it as a condition of the loan, especially on longer-term financing, but that's a lender requirement, not a state mandate. If your lender does require it, you're generally free to purchase it from any provider, not just the dealership.
Where to Buy: Dealership vs. Private Insurance
This is where the cost difference gets real. Dealerships often charge a one-time gap fee ranging from $400 to over $1,000, and when you finance that fee into your loan, the total cost can exceed $1,100 over the life of the loan due to interest charges.
Compare that to adding gap coverage through your auto insurance provider, where it typically costs less than $100 per year as an endorsement to your existing policy. That's a fraction of the dealership price, and you can cancel it anytime once you no longer need it.
At The Insurance Loft, we regularly help Colorado drivers compare gap options across multiple carriers to find the most cost-effective coverage. Because we're independent and work with companies like Nationwide, Travelers, and Progressive, we can show you what's available without being locked into one option.
Common Questions About Colorado Gap Insurance
Do I really need gap insurance if I have a new car?
A new car is actually when you need it most. New vehicles depreciate fastest in the first two to three years, which is exactly when the gap between what you owe and what the car is worth tends to be largest. If you put less than 20% down, gap coverage is a smart safeguard.
How much does gap insurance usually cost per month?
Through a private insurer, you're typically looking at less than $100 per year, which breaks down to roughly $8 or less per month. Dealership gap fees are significantly higher and get even more expensive when financed into your loan.
Can I cancel gap insurance once I owe less than the car is worth?
Yes. Once your loan balance drops below your car's market value, gap insurance no longer serves a purpose. If you purchased it through your auto insurer, canceling is usually a quick phone call. If you bought it at the dealership, you may be entitled to a prorated refund, though the process can take more effort.
Does gap insurance cover my deductible if I get in a wreck?
Most gap policies do not cover your deductible. Some upgraded versions, sometimes called "gap plus" or "total loss protection," include deductible coverage, but standard gap insurance typically does not. Ask your insurer or agent about the specific terms before you buy.
Will gap insurance pay for a replacement car?
No. Gap insurance only covers the difference between your insurance payout and your remaining loan or lease balance. It does not provide funds for a down payment on a new vehicle or any additional amount beyond what you owe.
Making the Right Choice for Your Vehicle
Whether gap insurance is worth it for your situation comes down to a few straightforward questions. How much do you owe? How much is the car worth? And how long will it take before those two numbers meet?
If you're financing a new or late-model vehicle in Colorado with a low down payment, a long loan term, or a lease that doesn't include built-in gap protection, the coverage is almost certainly worth the cost. At less than $100 per year through most insurers, it's one of the cheapest forms of financial protection you can add to your policy.
The Colorado-specific fee caps under HB23-1181 give you leverage if a dealership tries to charge you an inflated price, but the smarter move is usually to skip the dealership gap product entirely and add the coverage through your auto insurance provider.
If you're unsure where you stand, The Insurance Loft can review your loan or lease terms, compare gap options across carriers, and help you decide whether the coverage makes sense for your specific vehicle. Reach out to our team for a no-pressure conversation about your options. Sometimes a five-minute review saves you thousands.
Recent Posts
Let’s work together
Call Us
800-409-9790
Email Address
info@theinsuranceloft.com
Address Business
123 High St London, United Kingdom