
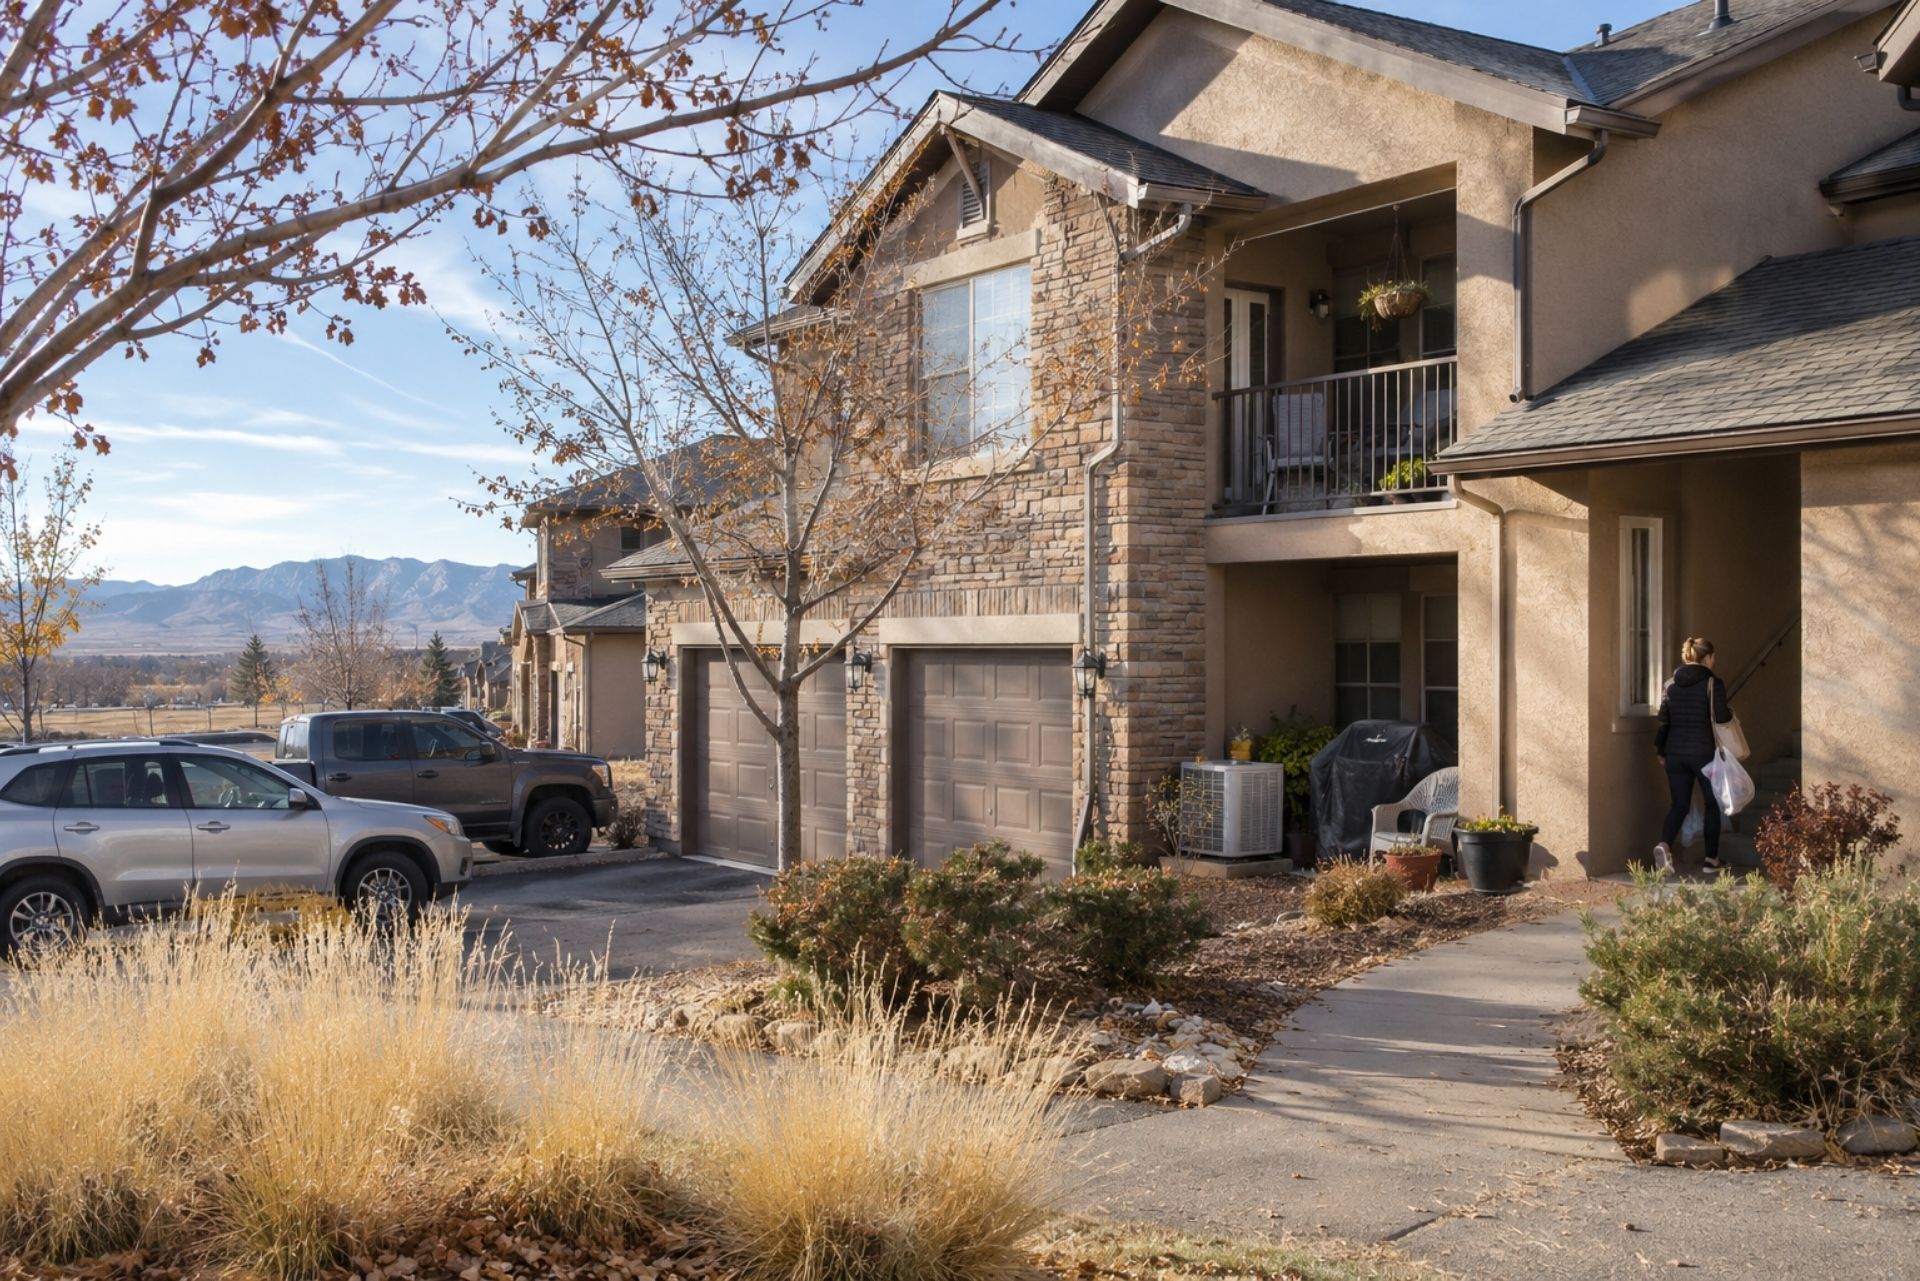
Picture a burst supply line on the fourth floor of a Broomfield condo building near the Flatirons Crossing area. Water runs through three units below before anyone shuts the valve. The HOA files a claim, the master policy kicks in, and then the letters start arriving: one owner owes a share of a hefty deductible, another learns her new flooring isn't covered, and a third finds out his "full coverage" never included the cabinets he paid to upgrade.
That scenario plays out more often than most condo owners expect. Broomfield sits squarely in the Front Range hail corridor, sees winter freeze-thaw cycles that crack pipes, and borders the Boulder County communities still recovering from the Marshall Fire. Each of those risks lands differently on a condo owner than on a single-family homeowner. The reason is simple: you share a roof, walls, and an insurance policy with your neighbors.
This guide to condo insurance in Broomfield, Colorado, covers what an
HO6 policy actually protects, where master policies leave you exposed, and how to price coverage without getting burned. If your last renewal notice made you wince, the details below should help you figure out whether you're paying for the right things.
Understanding Condo Insurance in Broomfield
An HO6 policy is the individual coverage a condo owner buys to sit alongside the association's master policy. The HOA insures the building as a whole. Your HO6 picks up what the association doesn't, and that line moves depending on your bylaws and declarations.
Broomfield's housing mix makes this tricky. You'll find older garden-style complexes off 120th Avenue, newer mid-rise buildings around Arista, and townhome-style communities that blur the line between condo and house. Two units a mile apart can carry completely different insurance obligations because their governing documents read differently.
Local risk shapes everything. Hail claims are routine across the Front Range, and many associations have responded by raising master policy deductibles, sometimes to a percentage of the building's value instead of a flat dollar amount.
Wildfire exposure along the open space edges matters too. A
2025 study found that 74% of Marshall Fire homeowners were underinsured, with 36% covered for less than 75% of replacement costs. Condo owners in neighboring Broomfield should treat that as a warning about their own limits.
By: Brian J. Cook
Founder & Managing Partner of The Insurance Loft
Bridging the Gap Between HO6 and Master Policies
The HO6 exists to fill gaps. Getting the gaps right starts with reading two documents side by side: your HOA's master policy summary and its declarations. Ask the property manager for both before you quote anything.
Dwelling Coverage (Walls-In)
Dwelling coverage on an HO6, often called Coverage A, protects the parts of your unit you're responsible for under the HOA documents. That can include interior drywall, flooring, cabinets, countertops, fixtures, and any improvements you or a previous owner made.
The most common mistake I see is setting this limit too low. Owners pick a round number like $25,000 without thinking about what it costs to replace quartz counters, luxury vinyl plank, and custom tile after a water loss. Contractor rates along the Front Range haven't gotten cheaper, either. Walk through your unit room by room and price out a rebuild of everything from the studs inward, then add a cushion.
Personal Property and Contents
Coverage C handles your belongings: furniture, electronics, clothing, kitchen gear, and the bikes in your storage unit. Make sure you're getting replacement cost rather than actual cash value, or you'll be paid for your five-year-old couch at garage-sale prices.
A few items need special attention:
- Jewelry and watches: Most policies cap theft coverage low, so schedule pricey pieces separately.
- Storage units: Off-premises property may have a reduced limit.
- Home office equipment: Business property often has its own small sublimit.
- Loss of use:
This pays for a hotel or rental if your unit becomes unlivable during repairs.
Master Policy Types vs. Individual Responsibilit
| Master Policy Type | What the HOA Covers | What You Typically Cover |
|---|---|---|
| Bare walls | Structure, roof, exterior, common areas | All interior finishes, fixtures, cabinets, flooring |
| Single entity | Structure plus original interior fixtures | Upgrades and improvements beyond original build |
| All-in (all inclusive) | Structure, fixtures, and owner improvements | Mainly contents, liability, and deductible exposure |
Even under an all-in policy, you aren't off the hook. The association's deductible still has to come from somewhere, and many bylaws pass it to the owner whose unit caused or suffered the loss.
Here's a pattern that trips people up in Broomfield: a building switches from single entity to bare walls at renewal to save on premiums, and nobody tells the owners. Your HO6 limit, which was fine last year, suddenly falls short. One thing to keep in mind is that HOA board minutes usually mention these changes, so skim them each year.
Protecting Against Loss Assessment and Liability
This is where an HO6 earns its keep. Loss assessment and liability coverage don't get much attention at signing, but they cause the biggest financial surprises after a claim.
HOA Special Assessments
When a covered loss hits common property, the association may assess every owner for its share of the master deductible or for damage exceeding the policy limits. Loss assessment coverage reimburses your portion.
Say a hailstorm damages the roofs across your complex and the master policy carries a percentage deductible that works out to a six-figure total. Split across 40 units, each owner could owe thousands. Default loss assessment limits on many HO6 policies are modest, often too low for today's high master deductibles. Colorado has pushed in this direction: state rules now require certain carriers to offer higher loss assessment minimums, up to 40% of the dwelling coverage, to address the gap created by large HOA deductibles.
Check your master deductible, divide by the number of units, then pick a loss assessment limit that clears that figure comfortably. Also confirm whether your policy pays assessments tied to a deductible, since some forms restrict that.
Personal Liability Limits
Liability coverage protects you when someone gets hurt in your unit or when you damage a neighbor's property. That burst supply line from the opening? If it started in your unit, the owners below may come after you for their deductibles and uncovered damage.
A $100,000 limit is common as a default, and I think it's too thin for most owners. Bumping to $300,000 or $500,000 usually costs little, and pairing your HO6 with an umbrella policy adds broader protection if you have significant assets to guard.
Factors Influencing Condo Insurance Costs in Colorado
Colorado premiums have climbed for years, driven largely by hail and wildfire losses. As one state official put it, "the market isn't going to solve [affordability] by itself", which tells you this isn't a short-term blip. HO6 policies tend to cost less than full homeowners coverage, but several factors push your rate up or down:
- Dwelling and contents limits: Higher limits mean higher premiums, though the jump is usually smaller than people fear.
- Your HO6 deductible: Raising it lowers premiums, but make sure you could actually pay it after a loss.
- Building age and construction: Older plumbing and electrical systems raise water and fire risk.
- Claims history: Prior water claims in your unit or by you personally can follow you.
- Credit-based insurance score: Colorado allows insurers to use credit information in rating, so stronger credit often means lower premiums.
- Wildfire exposure: Units near open space or grassland edges may see higher rates.
- Bundling: Pairing your HO6 with auto coverage frequently earns a multi-policy discount.
There's some relief coming. Starting October 1, 2026,
House Bill 25-1182 requires insurers to disclose their wildfire risk models and recognize science-based mitigation efforts, which may lead to premium discounts. Ask your HOA whether the building has completed any mitigation work you can point to.
Common Questions About Broomfield Condo Coverage
Do I legally need condo insurance in Broomfield? Colorado doesn't require it by law, but your mortgage lender almost certainly does, and most HOA bylaws require owners to carry an HO6.
Does my HO6 cover hail damage? Hail typically damages roofs and exteriors, which fall under the master policy. Your HO6 helps through loss assessment if the HOA bills owners for the deductible.
Is flood covered? No. Standard HO6 policies exclude flood, so ground-floor and garden-level units near drainage areas should consider a separate flood policy.
What about sewer backup? It's usually excluded unless you add a water backup endorsement. For lower-level units, that endorsement is worth the small added cost.
How much loss assessment coverage do I need? Start with your HOA's master deductible divided by the number of units, then add a buffer for possible assessments exceeding policy limits.
Will my rate go up if a neighbor's leak damages my unit? Claim handling varies by carrier and circumstance, so ask how a not-at-fault water claim affects your record before filing.
Making the Right Choice for Your Unit
The right HO6 policy starts with your HOA documents, not a quote form. Know your master policy type, find the deductible, and set dwelling, contents, loss assessment, and liability limits that reflect what a real Broomfield claim costs. Revisit those numbers every year, because associations change their coverage more often than owners realize.
When comparing quotes, match limits and deductibles exactly so you're comparing apples to apples. A cheaper policy with a tiny loss assessment limit isn't a bargain. Research how each carrier handles claims too, since that's when the policy actually matters.
That's where an independent brokerage helps. The Insurance Loft pairs you with a licensed advisor who reviews your HOA documents and compares condo coverage across carriers like Nationwide, Travelers, Safeco, and Chubb. Reach out to The Insurance Loft for a side-by-side review before your next renewal, and find your gaps before a burst pipe does.
COVERAGE FOR YOUR LIFE
Personal Insurance Plans That Protect What Matters Most
From your home and car to your family and pets — we cover it all.
GET THE ANSWERS YOU NEED
Common Questions About The Insurance Loft
We believe informed clients make better coverage decisions. Here are the questions we hear most often.
What does it mean to be an independent insurance agency?
An independent insurance agency like The Insurance Loft is not tied to a single insurance company. We are licensed to work with multiple carriers — including Nationwide, Travelers, Progressive, Safeco, Chubb, and others — so we can compare options and find the best policy for your needs. When you work with a captive agent, you only see what that one company offers. When you work with us, you see the full market.
This independence also means we represent you, not the carrier. When a claim arises or your coverage needs to change, your advisor advocates for your interests — not the insurance company's bottom line. That is the core of what makes The Insurance Loft different.
Where is The Insurance Loft located and who do you serve?
The Insurance Loft is headquartered in Greenwood Village, Colorado, in the Denver Tech Center area. We serve individuals and families throughout Colorado — from the Denver Metro and Front Range to Colorado Springs, Boulder, Fort Collins, mountain communities, and beyond. Our office is conveniently located at 5990 Greenwood Plaza Blvd, Ste 270, Greenwood Village, CO 80111.
Whether you are a longtime Colorado resident or just moved to the state, The Insurance Loft can help you find the right personal insurance coverage. Our advisors understand Colorado's specific risks and regulations, and they know which carriers offer the best coverage options for your area. Call us at 800-409-9790 or schedule a call online to get started.
What types of insurance does The Insurance Loft offer?
We offer a full range of personal and commercial insurance products. On the personal side, we cover home, auto, renters, life, motorcycle, umbrella, and pet insurance. For businesses, we provide general liability, commercial property, workers compensation, professional liability, business auto, and specialty coverage for industries like construction, food and beverage, brewery, and cannabis operations.
We also offer surety bonds for businesses that require them. Our goal is to be your single resource for every insurance need — personal or commercial — throughout your life and the life of your business. If you are unsure what coverage you need, schedule a call and an advisor will walk you through your options at no cost.
What carriers does The Insurance Loft work with?
The Insurance Loft partners with more than 19 trusted insurance carriers to give clients access to a wide range of options. Our featured carrier partners include Nationwide, Travelers, Progressive, Safeco Insurance, Chubb, and Hagerty Insurance for collector vehicles. Each carrier brings different strengths, pricing structures, and coverage specialties, which is why having access to multiple companies matters.
Because we work with a diverse group of carriers, we are not pressured to place policies with any single company. Your advisor reviews your situation, identifies which carriers best match your needs, and presents your options clearly. This process consistently delivers better coverage at competitive prices compared to going directly to a single insurance company.
How does The Insurance Loft handle the claims process ?
When you need to file a claim, your dedicated Insurance Loft advisor is your first call. We provide claims support through our Member Services team and guide you through the process with your carrier. You will not be left to figure it out alone. Our advisors help you understand what your policy covers, what documentation is needed, and what to expect from the timeline.
You can also access claims support directly through our Member Services portal at theinsuranceloft.com. Our goal is to make the claims process as clear and stress-free as possible so you can focus on recovery. For urgent claims assistance, contact our Customer Care team at 800-409-9790 during business hours, Monday through Friday, 9 AM to 6 PM.
Why should I review my insurance coverage every year?
Your life changes constantly — and your insurance should change with it. A new home, a new vehicle, a renovation, a new employee, a business expansion, or a change in your income can all affect how much coverage you need. Reviewing your policy annually helps make sure you are not paying for coverage you no longer need, and that you are not underinsured in areas where your exposure has grown.
The Insurance Loft advisors proactively reach out at renewal time to review your current policies and flag anything that needs attention. Major life events like buying a home, starting a business, getting married, or having children are all good reasons to schedule an earlier review. Contact your advisor or call 800-409-9790 to set up a coverage review at any time.
INSURANCE KNOWLEDGE, MADE SIMPLE
Learn From Our Resource Center
Practical answers to real insurance questions — written by the advisors who help clients every day.
CONTACT US
Phone Number: 1-800-409-9790